Instant payments have made money transfers faster than ever. Unfortunately, fraudsters are taking advantage of that speed.
A suspicious transaction can move through a banking network in seconds, often before traditional fraud systems identify the warning signs. For banks, the challenge is no longer just detecting fraudulent activity but stopping it before funds move.
According to the UK Payment Systems Regulator, £316 million, representing 88% of losses from eligible authorised push payment (APP) scams, was reimbursed over the 18 months ending March 2026. While reimbursement helps victims recover losses, preventing fraud requires faster risk decisions.
As banks prepare for 2027, real-time payment fraud detection must become part of payment infrastructure rather than a separate monitoring process.
Here are five engineering improvements banks should prioritize.
1. Move from Delayed Monitoring to Real-Time Data Streaming
Traditional fraud systems often process transaction data in batches, creating delays between payment activity and risk analysis.
For instant payments, even a short delay can reduce the opportunity to prevent fraud.
Banks need event-driven architectures that continuously process transaction activity, account behavior, device information, and authentication signals.
Technologies such as Apache Kafka and Apache Flink can support this through real-time data streaming and processing.
For example, when an account initiates several high-value transfers to unfamiliar beneficiaries, streaming systems can identify unusual activity before subsequent payments are executed.
Engineering priority: Build low-latency data pipelines that deliver fraud signals directly to payment decisioning systems.
2. Replace Rigid Rules with Context-Aware AI Risk Scoring
A high-value transaction is not necessarily fraudulent. What matters is whether it matches the customer’s normal behavior.
Traditional rule-based systems may flag every payment above a fixed threshold, creating false positives while missing sophisticated fraud patterns.
For example, a large payment from an unfamiliar device immediately after a password reset may indicate greater risk than the same payment from a recognized device.
Machine learning helps identify these relationships and supports more accurate risk decisions.
Engineering priority: Combine AI/ML models with established rules to improve fraud detection accuracy while minimizing unnecessary payment declines.
3. Connect Disconnected Banking Systems for Better Fraud Intelligence
Banks often manage customer information, transaction records, authentication, and fraud monitoring across separate platforms.
When these systems cannot exchange information quickly, fraud detection becomes less effective.
A fraud engine might recognize an unusual transfer but remain unaware that the customer recently changed devices or added a new beneficiary.
Secure APIs, data engineering, and centralized intelligence services can connect these signals without requiring banks to replace their entire infrastructure.
A unified data layer enables fraud models to access relevant transaction histories, account activity, and behavioral indicators.
Engineering priority: Establish secure, governed data integration that makes reliable fraud signals available in real time.
4. Integrate Fraud Detection Directly into Payment Workflows
Fraud alerts generated after payment execution may arrive too late to prevent financial losses.
Banks must integrate fraud assessment directly into payment processing.
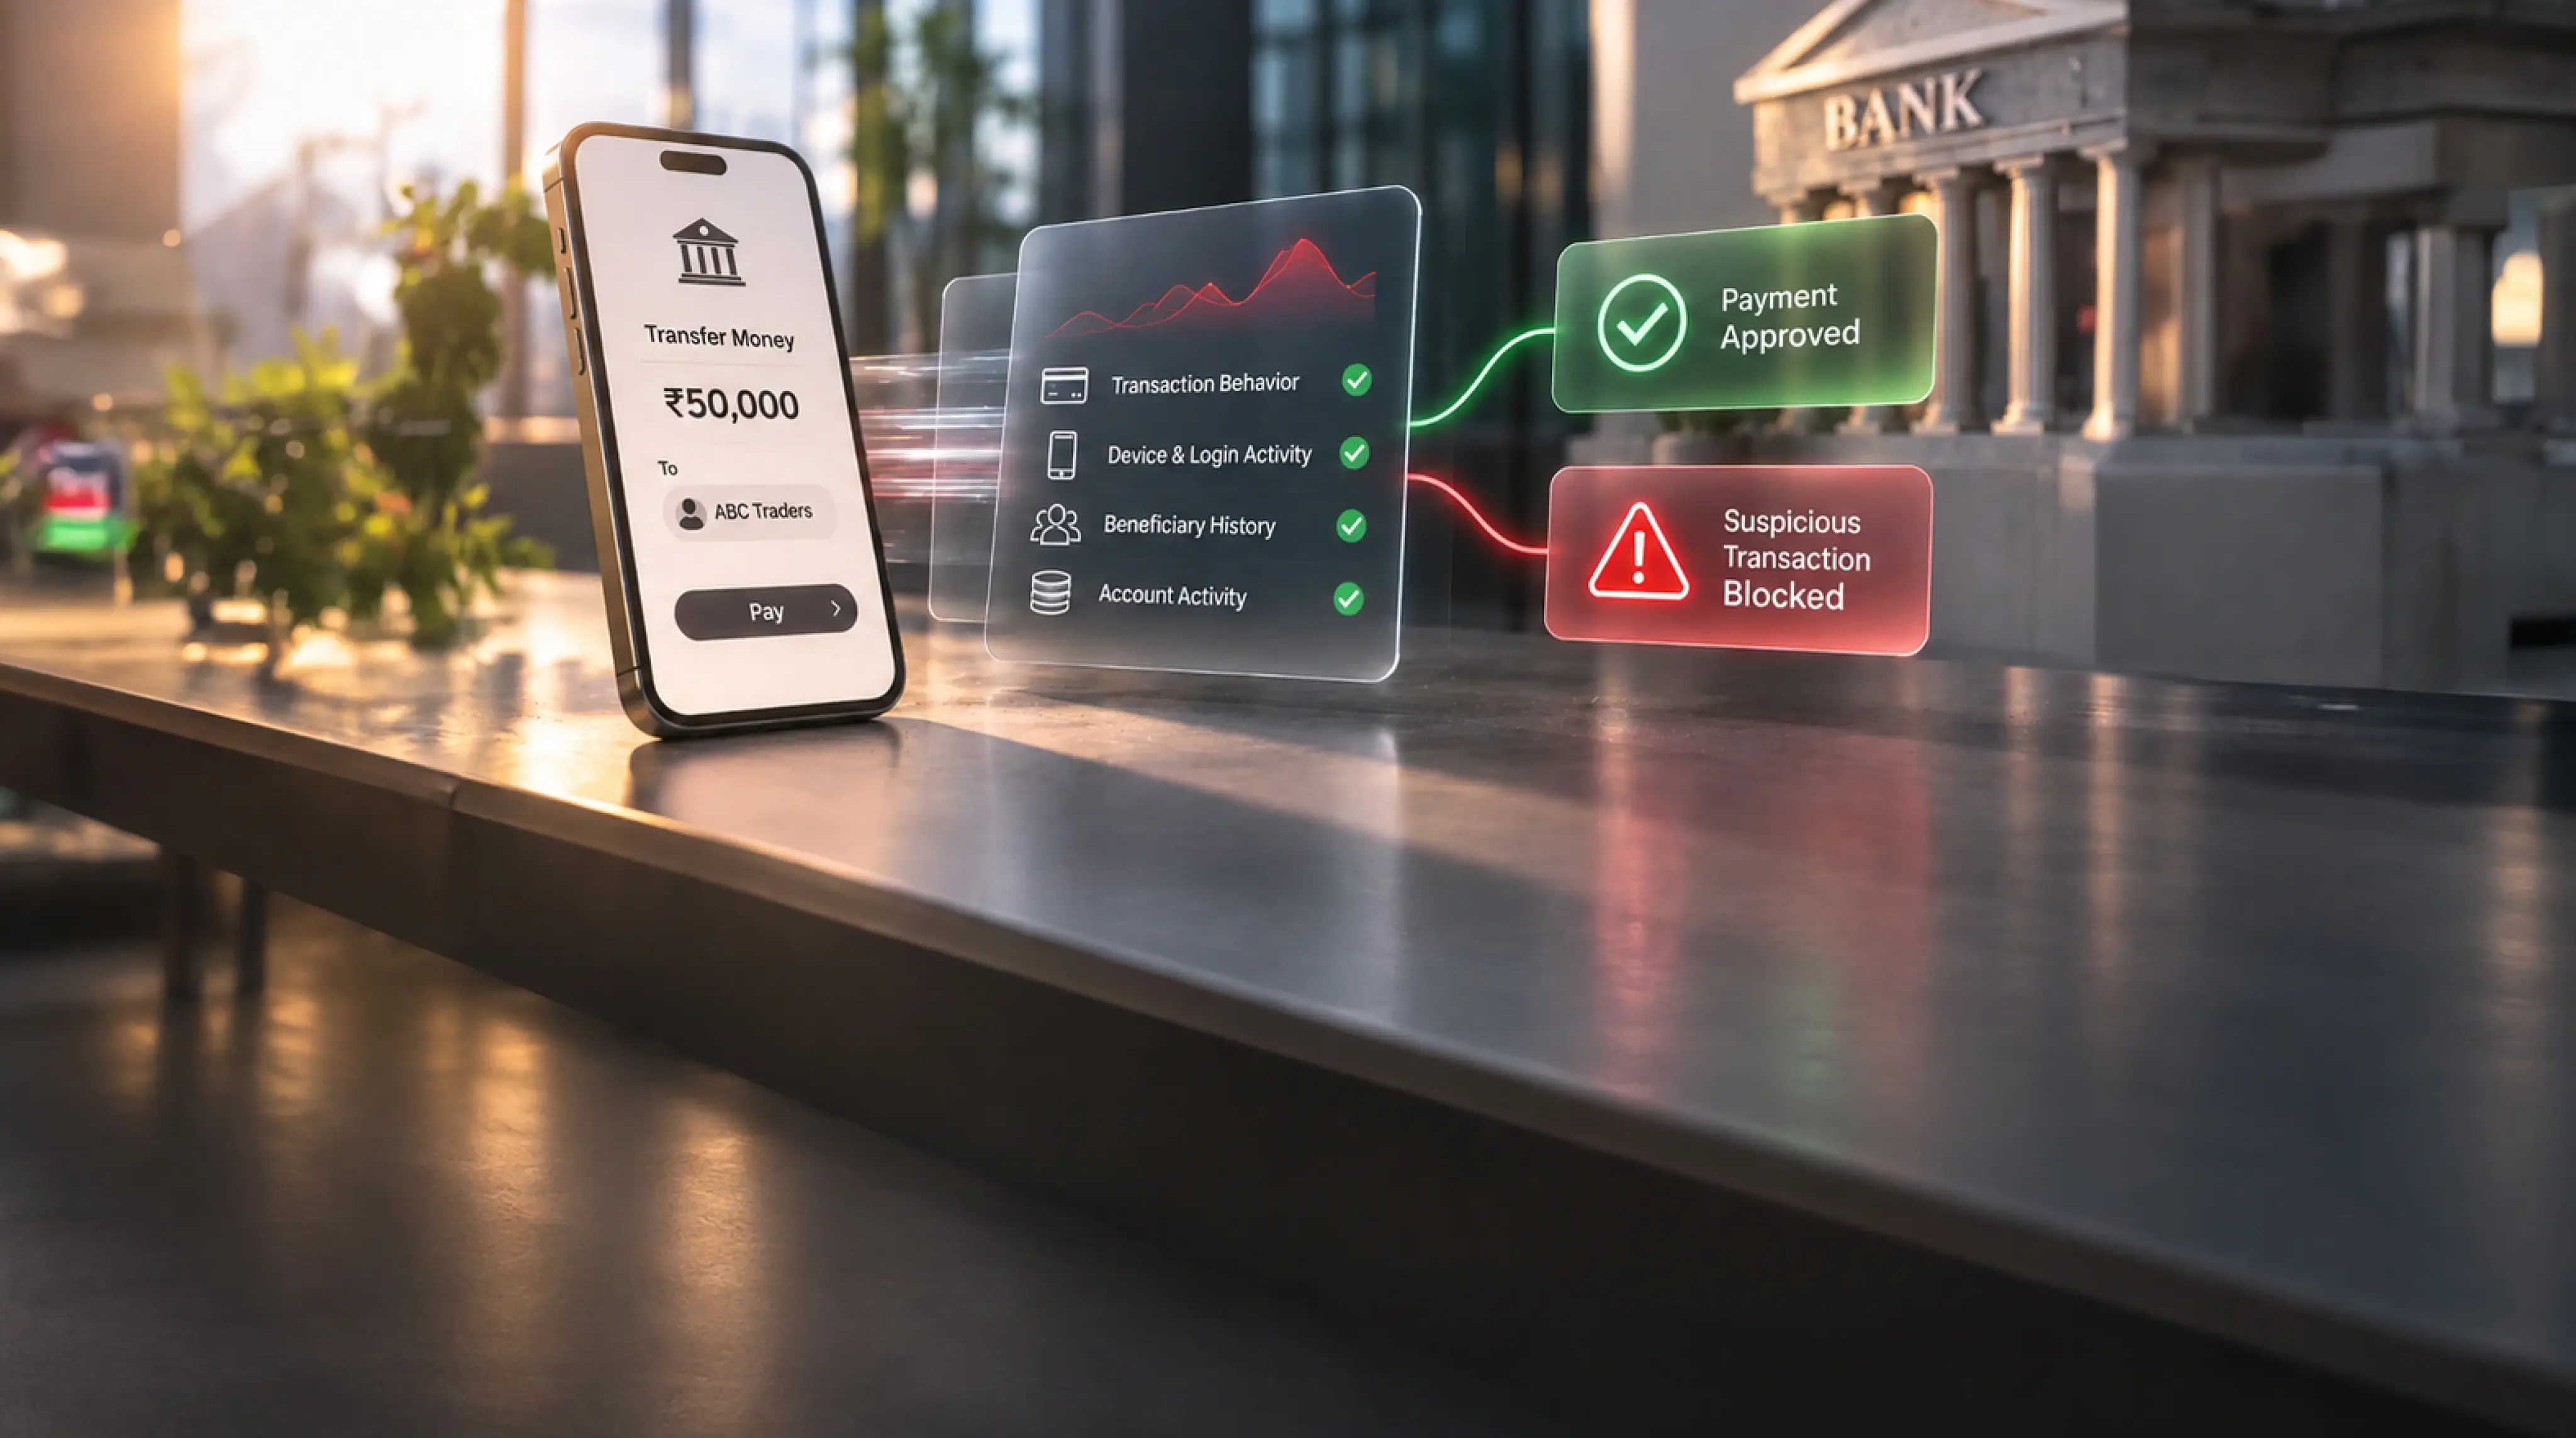
An effective workflow follows:
Payment Initiation → Data Analysis → AI Risk Scoring → Risk Decision → Payment Execution or Intervention
Depending on the risk assessment, banks can:
Approve low-risk transactions.
Request additional verification for suspicious payments.
Reject or temporarily hold high-risk payments where permitted.
Engineering priority: Embed low-latency fraud decisioning into payment workflows without compromising performance or availability.
5. Continuously Monitor Fraud Models and Reduce False Positives
Fraud patterns constantly evolve. A detection model trained on historical transactions may become less effective as new threats emerge.
Banks must continuously evaluate fraud detection performance using measurable indicators.
Key metrics include:
Fraud detection rate: Percentage of confirmed fraudulent transactions identified.
False positive rate: Legitimate payments incorrectly flagged as suspicious.
Decision latency: Time required to assess transaction risk.
Fraud loss rate: Financial impact of undetected fraud.
Model drift: Changes affecting AI model reliability.
Regular model evaluations, updated fraud data, and controlled retraining help maintain effectiveness.
Engineering priority: Establish continuous monitoring, explainable risk decisions, and governed model updates.
How NeoSOFT Supports Financial Fraud Prevention
Effective fraud prevention requires AI expertise, reliable data infrastructure, secure integrations, and scalable financial technology.
NeoSOFT combines AI/ML, data engineering, digital banking, cloud modernization, and cybersecurity to help financial institutions strengthen their technology foundations.
Its experience includes developing an AI-powered insurance fraud detection solution that uses machine learning and natural language processing to identify suspicious claims and prioritize investigations.
NeoSOFT has also engineered intelligent financial information systems and automated document processing solutions that improve data accessibility and reduce manual effort.
These capabilities support banks and FinTech companies seeking to modernize fraud intelligence and strengthen digital financial systems.
Conclusion: Faster Payments Need Faster Fraud Decisions
As instant payments become standard, banks cannot depend solely on traditional fraud monitoring.
Real-time data streaming, AI risk scoring, connected banking systems, payment-level controls, and continuous model monitoring can strengthen fraud prevention.
The objective is clear: identify suspicious transactions before funds move without slowing legitimate payments.
Meet NeoSOFT’s experts at Singapore FinTech Festival 2026, Booth 4D32, Singapore EXPO, from 18–20 November 2026, to discuss AI, digital banking, and cybersecurity solutions. Connect with our experts at info@neosofttech.com.
Frequently Asked Questions
1. What is real-time payment fraud detection?
It uses transaction data, behavioral analytics, and AI/ML models to identify suspicious payments quickly enough to support intervention before execution.
2. How does AI improve payment fraud detection?
AI analyzes transaction patterns, customer behavior, and risk indicators to detect suspicious activity that traditional rules may miss.
3. Why do instant payments increase fraud risks?
Instant payments leave limited time to identify suspicious activity and intervene before funds are transferred.
4. How can banks reduce false positives?
Banks can combine behavioral analytics, AI risk scoring, contextual transaction data, and continuous model monitoring to improve accuracy.
5. What technologies support real-time fraud detection?
Common technologies include Apache Kafka, Apache Flink, machine learning, secure APIs, and low-latency fraud decisioning systems.
Africa’s digital economy is expanding, but adopting cloud platforms and artificial intelligence alone will not guarantee business growth.
According to the GSMA Mobile Economy Africa 2026 report, mobile technologies and services contributed $240 billion to Africa’s economy in 2025, representing 7.8% of GDP. This contribution is projected to reach $290 billion by 2030.
Yet significant challenges remain. Legacy systems, disconnected enterprise applications, inconsistent data quality, and cybersecurity risks can limit the value of digital investments.
For African enterprises, the next stage of digital transformation requires more than introducing new technologies. It demands reliable engineering foundations that connect existing systems, support intelligent operations, and deliver measurable business outcomes.
As organizations prepare for 2027, five engineering priorities will determine how effectively they translate digital ambition into enterprise-wide results.
1. Modernize Legacy Systems Without Disrupting Business Operations
Many established enterprises depend on legacy systems that support critical banking, telecommunications, retail, and operational processes. Replacing these systems entirely can introduce significant cost, complexity, and business risk.
The priority should be incremental enterprise modernization, allowing organizations to upgrade essential capabilities while maintaining operational continuity.
A practical approach includes:
Identifying legacy applications that restrict scalability and integration.
Introducing API-based connectivity between existing and modern platforms.
Modernizing high-impact applications through modular architectures.
Migrating suitable workloads to cloud environments in controlled phases.
For example, financial institutions can modernize customer-facing applications while retaining reliable core banking infrastructure and introducing secure integrations.
With the right application modernization strategy, enterprises can reduce technical debt, improve system flexibility, and accelerate new digital service delivery without unnecessary disruption.
2. Build Reliable Data Foundations Before Scaling Enterprise AI
AI adoption is accelerating across African industries, from financial services and telecommunications to healthcare and retail.
However, AI cannot consistently deliver reliable outcomes when enterprise data is fragmented, inaccessible, or inaccurate.
Organizations often store customer, operational, and financial information across disconnected platforms. Without effective integration and governance, AI models may produce inconsistent results or remain restricted to experimental projects.
Building an enterprise-ready AI foundation requires:
Integrating structured and unstructured data from multiple business systems.
Establishing data quality, ownership, and governance standards.
Developing scalable data pipelines for analytics and AI applications.
Deploying AI models with continuous monitoring and performance evaluation.
Consider a telecom operator using predictive analytics to anticipate network failures. The effectiveness of its models depends on timely access to network performance data, maintenance records, and operational information.
By strengthening data engineering capabilities, businesses can move beyond isolated AI pilots toward applications that support real operational decisions.
3. Connect Cloud, Applications, and Enterprise Platforms Through APIs
Cloud migration is only one part of enterprise transformation. The greater challenge is ensuring that applications, infrastructure, and business processes work together.
Disconnected systems create duplicate data, manual workflows, delayed decisions, and inconsistent customer experiences.
API-led integration and cloud-native engineering help organizations overcome these limitations by connecting core applications with modern digital services.
Enterprises should prioritize:
API-first architectures that enable secure information exchange.
Hybrid and multi-cloud strategies aligned with business requirements.
Microservices and containerization where modularity delivers value.
Automated deployment, infrastructure management, and application monitoring.
For retail and e-commerce businesses, connecting inventory management, payments, logistics, and customer platforms can improve order visibility and streamline fulfillment.
Similarly, telecom operators can integrate customer management, billing, and service assurance systems to improve operational coordination.
The objective is not simply to move workloads to the cloud, but to create connected enterprise environments that support business growth.
4. Embed Cybersecurity into Every Stage of Digital Transformation
As African enterprises expand digital services and cloud adoption, their exposure to cyber threats also increases.
Cloud misconfigurations, insecure APIs, identity-related attacks, and vulnerabilities in legacy applications can compromise sensitive information and interrupt critical operations.
Cybersecurity must therefore be integrated into technology planning rather than introduced after deployment.
A security-first engineering approach should include:
Zero Trust principles and identity-based access controls.
Secure application development and continuous vulnerability assessment.
Cloud security monitoring and configuration management.
Encryption, data protection, and incident response readiness.
Security validation throughout software delivery processes.
For banking and payment platforms, integrating security throughout application development helps protect transactions and maintain customer trust.
For enterprises operating across multiple African markets, security architecture must also account for applicable national data protection and regulatory requirements.
Embedding cybersecurity into modernization initiatives strengthens operational resilience while reducing the risk of costly disruptions.
5. Measure Digital Transformation Through Business Outcomes
Technology implementation does not automatically translate into business value.
An enterprise may successfully migrate applications to the cloud or deploy an AI solution without achieving meaningful improvements in productivity, service delivery, or operating costs.
The fifth priority is establishing measurable business objectives before committing to large-scale technology programs.
Organizations should evaluate transformation initiatives against outcomes such as:
Reduced application downtime and faster recovery.
Lower operational costs through process automation.
Improved customer onboarding and service response times.
Faster software deployment and shorter release cycles.
Increased transaction processing capacity and operational efficiency.
For example, an AI-powered customer service platform should be assessed not merely by deployment success, but by its impact on resolution time, service quality, and cost per interaction.
Connecting engineering investments with measurable performance indicators enables CIOs and technology leaders to prioritize initiatives that deliver lasting business value.
Africa Tech Festival 2026: Turning Technology Priorities into Execution
These five priorities reflect the interconnected technology challenges being discussed at Africa Tech Festival 2026, taking place from 17–19 November at the Cape Town International Convention Centre.
With its six pillars spanning Telecoms & Connectivity, Data Centres, AI, Cybersecurity, Startups, and Digital Transformation, the event highlights the importance of building a connected, secure, and scalable digital economy.
As enterprises look toward 2027, execution will matter as much as innovation.
With over 25 years of engineering experience, NeoSOFT supports enterprises through AI/ML, cloud and application modernization, cybersecurity, data engineering, and digital product development.
At Africa Tech Festival 2026, NeoSOFT will engage with technology leaders and enterprises to explore how these capabilities can address complex modernization challenges and accelerate measurable business outcomes.
Connect with NeoSOFT’s experts to discuss your enterprise technology priorities and explore opportunities for engineering-led digital transformation.
1. What are the biggest challenges in Africa’s digital transformation?
Legacy infrastructure, disconnected applications, data quality issues, cybersecurity threats, and uneven digital access are among the challenges organizations must address to scale digital services.
2. Why is enterprise modernization important for African businesses?
Enterprise modernization improves application scalability, system integration, operational efficiency, and the ability to introduce new digital products without replacing every existing system.
3. How can African enterprises scale AI beyond pilot projects?
By improving data quality, integrating enterprise systems, establishing AI governance, and measuring production performance against defined business outcomes.
4. What role does cybersecurity play in digital transformation?
Cybersecurity protects applications, sensitive information, digital transactions, and business operations while helping enterprises maintain compliance and customer trust.
5. How can businesses measure digital transformation ROI?
Organizations can track measurable improvements in operating costs, application performance, process efficiency, deployment speed, customer experience, and revenue-related outcomes.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.