Banks have more reasons to address the need to modernise than at almost any time in the last 20 years, and their related activity is having to adopt a pace far outstripping much of what they built their own systems on.
Customer expectations have permanently changed from instant, mobile-first and personalised service.
Fintech challengers and digital banks have continued to take share in payments, loan and everyday banking. Most established institutions meanwhile are still running core processes on infrastructure that was never intended to run in real-time, or even have open APIs or be AI-driven decisioning.
In this context, digital transformation in banking has transitioned from a technology initiative to a priority at the board level.
With banks in particular, this pressure is coming from all directions at once: outdated tech that inhibits the speed of product development; an Open Banking/Open Finance agenda that increases the demands and complexity of data sharing and interoperability; dire regulatory expectations associated with growing cyber-resilience and operational resilience, as well as the sheer cost to continue to run parallel systems in your quest to innovate.
Banking and digital transformation are now inseparable, with technology decisions affecting the competitive position as directly as strength on the balance sheet. Bank digitalisation is a key part of this shift, as technology decisions go beyond introducing new mobile apps or refreshing the user experience. None of these are fixed with a new mobile app or a UX refresh.
True digital transformation in banking runs deep, all the way through the core technology stack, the data architecture and operating model – not just the front end customer facing layer.
In this guide, we explore what digital transformation really is for banks – how did it get to the stage where it was no longer optional, which areas are institutions targeting with their investments and building a strategy that stands up in the eyes of regulation and operationally.
Digital Transformation in Banking Definition To put it simply, banking digital transformation is too often equated with “going digital”- deploying a mobile app, digitising an existing paper form or pushing some call centre process online. Digitalisation in banking goes beyond these basic changes by improving existing banking processes through digital technologies.
That framing understates what is actually required. Across the banking industry more broadly, this narrow definition is common – and it consistently under-delivers, because it stops at the customer-facing layer instead of the systems behind it.
At its core, digital transformation in banking and financial services is the redesign of how a bank operates, using technology to change all five elements simultaneously:
Technology modernization– moving away from monolithic, tightly coupled core systems towards modular, API-enabled architecture that can evolve without a multi-year replatforming project every time.
Process transformation– redesigning workflows (onboarding, credit decisioning, claims, servicing) around automation and straight-through processing, rather than digitising a manual process step by step.
Data integration– breaking down the data silos that build up across decades of mergers, product launches and point solutions, so customer and risk data can be used consistently across channels.
Customer experience– building consistent, personalised experiences across mobile, web, branch and contact centre, rather than a good app sitting on top of a fragmented back end.
Operating model transformation– shifting from siloed, project-based delivery to product-led, cross-functional teams that can ship and iterate continuously.
Digital banking transformation, in other words, is an enterprise change programme that happens to be delivered through technology – not a technology project with some change management attached.
Banks that treat it as the latter tend to end up with a modern front end bolted onto an unchanged, high-cost back end. Genuine banking digital transformation requires all four elements to move together, not in isolation.
Why Are Banks Investing in Digital Transformation?
The drivers of digital transformation in investment banking vary by institution, but most banks are responding to a combination of common business and technology pressures. Together, these pressures are accelerating change across the banking industry.
Rising Customer Expectations
Certain retail and business banking customers now inevitably compare their bank with the best digital experience they’ve ever had anywhere – not just another bank. Instant onboarding, transparency into payments as they happen, proactive alerts when potential fraud occurs and contextual financial advice have transitioned from differentiators to base table stakes.
Failing on any of those is now more frequently reflected in attrition and complaint volumes as well as satisfaction scores. Corporate banking digital transformation is experiencing a similar trend: business customers have come to expect the same real-time visibility and self-service capabilities in cash management, trade finance and lending as they enjoy with consumer banking apps. Recognized with the Best CX Transformation award, organizations demonstrate how customer-centric digital innovation can improve business banking experiences.
Legacy Technology and Core Banking Challenges
Many banks – particularly established retail and commercial banks – are still running core banking platforms that are decades old, heavily customised, and expensive to change safely. Every new product, regulatory change or integration has to work around this core, which slows time-to-market and increases the cost of even small changes.
This is often referenced as the most challenging limiting factor of speed to transformation and it helps explain why banking digital transformation programmes so very frequently start off on back end core systems rather than front-end customer-facing channels.
Competition from Digital-First Banks and Fintech Companies
Digital-only banks and fintechs had the benefit of designing their technology stacks on a blank slate, in contrast to more traditional banks who are forced to work with legacy infrastructure that was long outdated. They can promote products quicker, experiment with pricing and features more openly, and provide a better onboarding experience.
It has also required legacy banks to compete on speed and experience, which are now competing directly with trust and a branch presence – two areas where they used to lead.
Open Banking and Open Finance
Open Banking plays an important role in digital transformation in banking, enabling banks to securely share customer-permissioned financial data with authorised third-party providers through APIs. Open Finance extends this approach beyond traditional banking to a wider range of financial services, creating opportunities for integrated financial products, personalised customer experiences, and data-driven innovation.
To support banking digital transformation, financial institutions need robust API management, secure data-sharing frameworks, clear customer consent mechanisms, and effective data governance. These capabilities help banks integrate fintech solutions, modernise legacy systems, strengthen regulatory compliance, and develop innovative digital banking services while protecting customer data.
AI and Intelligent Automation
In financial services, AI adoption has progressed from pilot applications in areas such as fraud detection, credit risk scoring and customer service automation. However, the operational and business case for automating manual rules-based work through AI is compelling enough that practically every institution now has one or more live automated use cases even while banks face pressure to implement responsible, explainable and fair AI.
Cybersecurity and Operational Resilience
Financial services regulation places significant emphasis on operational resilience – the ability of a bank to keep delivering important business services through disruption, not just to prevent it. As banks modernise and expose more services via APIs and cloud infrastructure, heightened cyber risks mean security and resilience have to be designed in from the start, not layered on afterwards. This is now as central to transformation planning as customer experience or cost reduction.
Retail Banking Digital Transformation
Retail banking digital transformation focuses on improving everyday banking experiences through mobile banking, digital payments, automated services, and personalised financial solutions. It helps banks deliver faster transactions, seamless customer interactions, and more efficient service delivery.
Private Banking Digital Transformation
Private banking digital transformation uses advanced technologies, data analytics, and AI-driven insights to deliver personalised wealth management and investment services. It enables private banks to improve client relationships, streamline portfolio management, and provide secure digital advisory experiences.
Commercial Banking Digital Transformation
Commercial banking digital transformation helps financial institutions modernise business banking services through automated lending, digital cash management, and integrated financial platforms. It improves operational efficiency, simplifies business transactions, and supports better financial decision-making for corporate clients.
Key Areas of Digital Transformation in Banking
Core Banking Modernization
Core banking modernization is where most transformation programmes eventually have to go, even if they start elsewhere. Within the digital transformation banking industry conversation, core modernization is usually the least visible work and the most consequential. The challenges are well understood: legacy cores are difficult to scale, expensive to integrate with newer systems, and risky to change without disrupting live services.
The direction most banks are taking is incremental rather than “big bang” – decomposing monolithic cores into more modular components, introducing cloud-native architecture around the edges, and using API layers to decouple the pace of front-end innovation from the pace of core change. This allows faster product development without requiring a full core replacement as a prerequisite for every improvement.
For banks assessing where to start, the practical question is usually not “replace or keep” but “which parts of the core create the most drag on the business today, and can they be moderised in isolation.” Partners with genuine banking technology capabilities can help scope this kind of phased modernization realistically, based on what has actually worked in comparable environments – since digital banking transformation tends to succeed or stall based on how well this phase is sequenced.
Open Banking and Open Finance
Beyond regulatory compliance, Open Banking has created a genuine strategic opportunity for banks. A well-designed API ecosystem allows a bank to integrate with third-party providers, accounting software, budgeting tools and lending platforms – extending its own product reach without building everything internally.
This works in both directions. Banks can leverage third-party data (with the customer’s consent) to complete an overall view of a customer’s financial status which will help in making more accurate credit decisions and offering them more useful products. They can also expose their own APIs to support ecosystem partnerships, embedding banking services within other platforms that customers already use.
It’s non-trivial from a technical perspective at all: secure API management, solid controls for consent and data-sharing as well as monitoring to minimise operational risk if third-parties are exposing integrations.
Banks that treat API strategy as core infrastructure – rather than a compliance checkbox – tend to get more commercial value out of Open Banking and Open Finance over time. This is particularly relevant to corporate banking digital transformation, where API connectivity to treasury, ERP and accounting platforms is increasingly a deciding factor for business customers choosing a banking partner.
Cloud Transformation
Most transformation initiatives are underpinned by cloud adoption, because it alters what is possible regarding cost, scalability and resilience. By moving workloads to the cloud, banks can now scale their infrastructure on demand rather than over-provisioning for peak load year-round. It also aids in faster recovery and enhanced resilience posture as cloud providers provide options for redundancy and failover which are cost prohibitive to replicate on-prem.
Usually, Integration is the most difficult half. With most banks moving towards at least hybrid or multi-cloud approaches, using on-prem for regulatory reasons, latency or legacy-dependency use cases and the cloud for analytics, customer facing applications and pretty much anything windows workloads. A clear view of which systems you are going to implement with a cloud-native design and a feasible migration order that can ensure service continuity throughout the process is required to get this right. This is where higher-order enterprise digital transformation services usually kick in – supporting banks to sequence cloud migrations alongside broader modernization roadmaps as opposed to being treated as an isolated core infrastructure project.
AI and Intelligent Automation
AI use cases in banking have matured well beyond chatbots. The most established applications include:
Fraud detection– automatic analysis of transactions in real-time. Anomalies are flagged quicker and more accurately than rules engines.
Customer support –Artificial Intelligence that resolves common queries and presents the remaining complex support tickets to the most appropriate human agent.
Document processing– automated extraction and validation for KYC documentation, loan applications and account opening paperwork.
Risk analysis– models that support credit decisioning and portfolio risk assessment with more current, granular data than traditional scoring approaches.
Operational automation– minimizing the need for manual intervention for reconciliations, reports, and back office processing.
Personalized banking– Using behavioral and transactional data to suggest appropriate banking products and services, along with customized nudges at real-time banking interactions.
The practical constraint for banks is governance: AI models used in credit or risk decisions need to be explainable and auditable, and data used to train or run them needs to meet strict handling and privacy standards. Banks that get the most value from AI tend to introduce it in well-bounded, high-volume processes first – where the business case is clear and the governance requirements are manageable – before expanding into more complex decisioning use cases.
Data Modernization and Personalization
Every other transformation initiative depends on data that is accurate, accessible and governed. For most banks, this is the least visible but most foundational part of the transformation agenda.
A unified view of customer data – pulled together from product silos, channels and, increasingly, third-party sources – is what makes real personalization possible: relevant offers, proactive alerts, and servicing that doesn’t require a customer to repeat themselves across channels. It’s also what makes advanced analytics and AI models reliable, since model quality is capped by the quality and completeness of the underlying data.
Strong data governance is not optional here. Clear ownership, lineage and quality controls are what allow a bank to use data confidently for decisioning while remaining able to demonstrate compliance to regulators and auditors. Banks that invest in data modernization early tend to move faster on every subsequent initiative – AI, personalization, Open Banking integrations – because the foundational work is already done.
Challenges Banks Face During Digital Transformation
Transformation programmes rarely fail for lack of ambition. They tend to stall on a predictable set of operational and organisational challenges:
Complex legacy infrastructure– deeply customised systems accumulated over decades, often poorly documented, make even routine changes slow and risky.
Data silos– customer and product data spread across disconnected systems limits the value of any single modernization effort.
Cybersecurity risks– a larger attack surface as systems become more interconnected and API-driven, requiring security to be designed in rather than retrofitted.
Regulatory requirements– banks operate under close FCA and PRA scrutiny, and transformation initiatives need to be planned with compliance and reporting obligations in mind from the outset, not addressed as an afterthought.
Integration complexity– connecting modern applications with legacy cores, third-party APIs and existing data warehouses is rarely straightforward.
Skills gaps– demand for cloud, AI and modern engineering skills often outpaces what banks can hire and retain internally, particularly outside London.
Balancing innovation with operational stability– the pressure to move fast has to be weighed against the reality that core banking services cannot go down.
Managing transformation without disrupting critical services– most transformation happens while the bank is still fully operational, which rules out the kind of clean-slate rebuilds that are easier in theory than in a live, regulated environment.
None of these challenges, including the tech talent gap, are reasons to delay transformation but they are reasons to sequence it carefully, with realistic timelines and a clear-eyed view of dependencies.
Building a Successful Bank Digital Transformation Strategy
A workable bank digital transformation strategy tends to follow a consistent set of steps, even though the specifics differ by institution.
Assess the existing technology landscape. Before committing to any roadmap, banks need an honest inventory of what’s running where, what’s end-of-life, and where the real constraints sit. Without this, transformation plans are built on assumptions rather than evidence – and it’s the step most digital transformation in banking initiatives skip under pressure to show early progress.
Identify high-impact transformation priorities. Not every system needs modernizing at once. Prioritising the initiatives that unblock the most value – whether that’s a specific product line, a customer journey, or a compliance requirement – keeps early transformation work focused and demonstrably useful.
Modernise critical systems gradually. Phased modernization reduces risk compared with wholesale replacement, and lets the bank validate each stage before committing further investment. This matters more in banking than most industries, given the operational stakes of getting it wrong.
Build an API and integration strategy. APIs are what let modern applications, third-party partners and Open Banking requirements connect to the bank’s systems without requiring every underlying system to be rebuilt first. Treating API design as strategic infrastructure – not an afterthought – pays off across every subsequent initiative.
Strengthen data and analytics capabilities. As covered above, data quality and governance underpin AI, personalization and reporting. This step is often undervalued relative to more visible initiatives, but it determines how much value those initiatives can actually deliver.
Introduce automation and AI responsibly. Starting with well-defined, high-volume processes builds internal confidence and governance maturity before extending AI into more sensitive decisioning areas.
Improve cybersecurity and resilience. Security and resilience need to be built into the architecture of every new system, not added after deployment – particularly as more services become API-accessible and cloud-hosted.
Measure transformation outcomes. Clear metrics – cost-to-serve, time-to-market for new products, customer satisfaction, operational incident rates – keep transformation accountable to business outcomes rather than technology delivery for its own sake. A bank digital transformation strategy is only as credible as the outcomes it can demonstrate against these measures.
The Role of Technology Partners in Banking Transformation
Few banks have the full range of in-house capability required to execute a transformation programme of this scope end to end – from legacy application modernization and core banking platform development, through API integration, cloud transformation, AI and automation, data engineering, digital customer experience and enterprise architecture. Skills gaps in cloud engineering and AI, in particular, are widespread across the sector.
An experienced technology digital transformation partner can extend internal teams with the specialist capability needed at each stage – helping assess legacy systems realistically, design integration and API strategies that hold up under regulatory scrutiny, and deliver cloud and AI initiatives without requiring the bank to build every capability from scratch. This commitment to innovation and industry-leading solutions reflects the standards recognised by the Excellence in Fintech Award.
NeoSOFT works with financial services organizations across these areas – legacy modernization, cloud transformation, data engineering and AI-enabled automation – supporting institutions that need to move faster on transformation without compromising on the operational and regulatory standards banking requires. NeoSOFT’s financial services technology solutions are built around that combination: technical depth, delivered in a way that respects how regulated, live banking environments actually need to change.
The Future of Digital Banking
Several directions are becoming clearer as banking transformation matures:
AI-powered banking operations– AI moving from point solutions towards being embedded across fraud, risk, servicing and operations as a standard part of how banks run.
Agentic AI, where relevant– early exploration of AI systems that can carry out multi-step tasks with oversight, particularly in back-office and operational processes, though adoption in customer-facing and decisioning contexts remains cautious and governance-led.
Open Finance– extending Open Banking’s data-sharing principles across a broader range of financial products, creating more opportunities for integrated, ecosystem-based services.
Embedded finance– banking services delivered through non-bank platforms via APIs, extending banks’ distribution beyond their own channels.
API-driven banking ecosystems– API strategy becoming as central to bank technology planning as the core platform itself.
Real-time decisioning– faster credit, fraud and servicing decisions supported by better data and more current risk models.
Hyper-personalization– using unified data to move from segment-based offers to genuinely individual relevance.
Modern core banking– continued, incremental movement away from monolithic legacy cores towards modular, API-enabled architecture.
Increased focus on security and resilience– as systems become more interconnected, resilience planning becomes as important as innovation itself.
None of these represent a wholesale reinvention of banking. They’re a continuation of the same modernization trajectory banks are already on – just with the pace and sophistication increasing. The next phase of digital banking transformation is less about new capabilities in isolation and more about how well they integrate with what already exists, which is why banking digital transformation increasingly depends on sequencing and architecture as much as on the technology itself.
Conclusion
Digital transformation in banking is not simply about launching new digital channels. For banks, it requires modernising the underlying technology ecosystem, improving data capabilities, creating more flexible operating models, and building secure, customer-focused digital experiences that hold up under real regulatory and operational scrutiny.
Across banking, the institutions making the most progress are the ones treating transformation as a continuous, sequenced programme – grounded in a clear assessment of their technology landscape – rather than a single project with an end date.
Financial institutions planning their next phase of transformation need a strategy that connects technology modernization with measurable business outcomes. NeoSOFT supports financial organizations across digital transformation, modernization, data, AI and enterprise technology initiatives.
FAQs
What is digital transformation in banking?
It’s the use of technology to redesign how a bank operates – modernising core systems, integrating data, automating processes and improving customer experience – rather than simply digitizing individual customer touchpoints.
Why is digital transformation important for banks?
Banks face rising customer expectations, competition from digital-first banks and fintechs, legacy technology constraints, and an evolving Open Banking and Open Finance landscape – all of which make continued modernization a competitive and operational necessity rather than an optional upgrade. In banking, banking and digital transformation have effectively become the same conversation.
What are the main challenges of banking digital transformation?
Common challenges include complex legacy infrastructure, data silos, cybersecurity risk, regulatory requirements, integration complexity, skills gaps, and the need to modernise without disrupting live, critical banking services.
How does Open Banking support digital transformation?
Open Banking’s API-based, consent-driven data-sharing model gives banks a foundation for third-party integrations, richer customer data and new product and partnership opportunities – extending what a bank can offer without building every capability internally.
What role does AI play in banking transformation?
AI supports fraud detection, customer service, document processing, risk analysis and operational automation. In banking, adoption tends to be most advanced in well-bounded, high-volume processes, given the explainability and governance requirements around AI-driven decisioning.
What is core banking modernization?
It’s the process of decomposing or replacing legacy core banking systems – often incrementally – to improve scalability, reduce integration friction, and enable faster product development, typically using API layers and modular, cloud-native architecture.
How can banks create a successful digital transformation strategy?
By assessing their current technology landscape honestly, prioritising high-impact initiatives, modernizing critical systems gradually, investing in API and data foundations, introducing AI and automation responsibly, strengthening cybersecurity, and measuring progress against clear business outcomes.
Poor data does not just slow decisions — it quietly distorts them. Executives cite unreliable data as a barrier to digital transformation.
The sophistication of your analytics infrastructure means very little if the data feeding it is unreliable. Before you ask what data quality is, consider this: every forecast, every risk model, every board-level dashboard is only as credible as the data it is built on. For finance leaders, that is not an abstract concern — it is a boardroom liability.
Data quality is, at its core, the degree to which data is accurate, complete, consistent, timely, and fit for its intended purpose. In financial services — where decisions carry regulatory weight and shareholder consequence — that definition carries enormous practical stakes.
What Is Data Quality, and Why Does It Demand Executive Attention?
At the enterprise level, why data quality is important is no longer a question asked only by data teams. It belongs in the C-suite agenda. Financial analytics programmes ingest data from dozens of sources: core banking systems, market feeds, CRM platforms, third-party data vendors, and regulatory repositories. Each handoff is a potential point of corruption.
Data integrity — the assurance that data has not been altered, corrupted, or lost in transit — is the bedrock on which accurate financial reporting stands. Without it, reconciliation fails silently, regulatory submissions carry latent errors, and strategic models produce outputs that appear precise but are fundamentally unsound.
Data Quality Checks: The First Line of Defence
Implementing structured data quality checks is not a back-office function — it is a risk management discipline. Systematic validation at every stage of the data pipeline ensures that anomalies are caught before they cascade into analytical outputs. These checks span completeness validation (are all required fields present?), referential integrity checks (do records relate correctly across systems?), range and format validation, and duplication detection.
For financial institutions, automated data quality checks reduce the manual burden on finance teams, accelerate period-close cycles, and significantly lower the risk of material misstatement. When integrated into a broader business analytics architecture, they shift the organisation from reactive data firefighting to proactive data governance.
The Link Between Data Quality and Financial Analytics Performance
High-quality data is not merely a prerequisite for data analysis — it is the multiplier that determines its value. Consider a scenario where your analytics team builds a sophisticated cash flow forecasting model. If the underlying transaction data contains duplicates, incorrect currency classifications, or missing counterparty identifiers, the model will produce confident-looking projections that are fundamentally miscalibrated.
The downstream consequences are significant: treasury decisions based on inaccurate liquidity positions, credit risk assessments that understate exposure, and performance benchmarks that misrepresent business unit contributions. In each case, the issue is not the analytics capability — it is the data that powers it.
Embedding data analytics best practices alongside a rigorous data quality framework ensures that your investment in analytics technology produces genuine intelligence rather than sophisticated noise.
Software Quality and Data Pipelines: An Overlooked Connection
Software quality is an often-underestimated dimension of the data quality conversation. The ETL pipelines, data warehouses, and integration layers that move financial data across systems must be held to the same rigour as the data itself. A transformation logic error in a pipeline can silently corrupt otherwise clean source data, producing downstream errors that are extraordinarily difficult to trace.
Organisations that treat software quality as separate from data quality are managing only half the risk. A mature financial analytics programme demands both validated data and reliable, well-tested systems to process it.
Building a Culture of Data Integrity
The technical infrastructure for data quality is necessary but insufficient on its own. Sustained data integrity requires cultural commitment — from the executives who set data governance priorities, to the analysts who flag anomalies, to the engineers who build the pipelines. Organisations that treat data quality as a shared organisational responsibility, rather than an IT function, consistently outperform those that do not.
This means establishing clear data ownership, investing in ongoing data quality monitoring, and making data health a visible metric at the leadership level — alongside revenue, margins, and operational KPIs.
Conclusion
Building and sustaining a high-quality financial analytics programme requires more than good intentions — it requires a technology partner with deep expertise in both data engineering and financial domain complexity. This is where NeoSOFT delivers a measurable advantage.
NeoSOFT’s data and analytics practice offers end-to-end capabilities — from designing scalable data warehouses and implementing automated data quality frameworks, to building predictive analytics solutions tailored for the financial services sector.
For CXOs evaluating their analytics roadmap, the question is not whether data quality matters — it is whether your current programme has the architecture, governance, and partner ecosystem to guarantee it. Reach out to experts at info@neosofttech.com and explore how we can future-proof your data programme.
Frequently Asked Questions
What is data quality, and why does it matter for financial analytics?
Data quality refers to how accurate, complete, consistent, and timely the data is. In financial analytics, it directly determines whether forecasts, risk models, and dashboards can actually be trusted for decision-making.
What are data quality checks, and how do they work?
They’re systematic validations built into the data pipeline — checking for completeness, referential integrity, correct formatting, and duplication — that catch errors before they cascade into financial reporting or analytics outputs.
How does poor data quality affect financial decision-making?
It produces confident-looking but miscalibrated outputs — inaccurate liquidity positions, understated credit risk, or misrepresented performance benchmarks — even when the underlying analytics models themselves are sound.
Is data quality an IT responsibility or a business-wide one?
It works best as a shared responsibility. Organizations that treat data quality as a leadership priority — with clear ownership, ongoing monitoring, and visibility alongside revenue and margin metrics — consistently outperform those that leave it solely to IT teams.
By mid-2026, digital commerce will have splintered. Not only does ChatGPT compete with Amazon, Alibaba, and Walmart, but it does so without owning a single warehouse. With a user base exceeding 1 billion MAU and extensive reach in both Indian and Middle Eastern markets, OpenAI isn’t just a research organisation; it’s now a force in transactions.
Instead of wondering how ChatGPT can support the buying process, we should wonder whether it will become one of the top 10 e-commerce platforms by transaction volume. For brands, this isn’t simply another platform to integrate; it represents the complete redefinition of their customer journey. According to various studies, AI-assisted consumers make purchases four times faster than ordinary e-commerce users. It means that ChatGPT is not entering the e-commerce market – it’s creating a brand new category called Agentic Commerce.
The Rise of the Invisible Marketplace: Why 2026 is the Tipping Point
The conventional e-commerce model revolves around Browse & Search. You visit the website, enter the relevant keyword, and browse through the grid layout. ChatGPT, on the other hand, has reversed the whole process. The age of agentic commerce has dawned, and more often than not, the buyer is an AI.
From Recommendation Engine to Transactional Agent
In early 2026, OpenAI introduced its Agentic Commerce Protocol (ACP), which it developed in collaboration with Stripe. The ACP isn’t just a button to make a purchase; it’s a system that enables ChatGPT to process merchant information, verify inventory in real time, and complete payment. Instead of the old-fashioned search boxes of 2024, ChatGPT operates more like a concierge, with the intent to hire the product to handle a task.
The Conversion Advantage: Quality Over Quantity
According to recent GA4 statistics on seven-figure brands, ChatGPT referral traffic currently converts 31% better than non-branded organic search traffic. That is precisely what we refer to as intent compression, and the reason why ChatGPT poses a danger to the top 10. By the time users click any link in ChatGPT, they are no longer browsing; they are already pre-qualified by an AI.
The Strategic Shift: Moving from Persuasion to Agent Legibility
For many years, marketing was focused on persuading the human mind. In the age of ChatGPT, where we are now in 2026, marketing revolves around ensuring that the machine can decipher information about the delivery windows and return policies within seconds.
Why Your Human Website is Your Biggest Bottleneck. An AI bot is unable to manage the vagueness that people can cope with. Annoying pop-up messages, poor HTML structure, and vague shipping descriptions (3-5 business days) are among the hurdles an AI bot faces. To be among the best ChatGPT bots, companies have started using MCP servers. These servers act as a virtual replica of your business, providing structured data directly to AI agents.gents.
The Universal Commerce Protocol (UCP) Mandate
The Universal Commerce Protocol, developed by Google and Shopify, was officially launched at NRF 2026. To qualify for placement within the top recommendations on ChatGPT, brands need to be compatible with UCP. This guarantees that whenever ChatGPT asks, “Can this be delivered to Dubai by Friday?” the response will be a definite “Yes,” and not just “Check shipping at checkout.”
Redefining the Funnel: The Collapse of Search, Compare, and Buy
In a traditional e-commerce ecosystem, the funnel is a multi-tab experience. In 2026, ChatGPT collapsed this funnel into a single, intent-driven interaction.
The End of the Lazy ROAS Brand Defence: Brands have used keywords for many years to fatten their ROAS figures. However, with more AI Agents in ChatGPT designed to ignore paid prioritisation and focus more on Outcome Optimisation, finding the right price-to-value and logistics becomes a top priority. Any brand that cannot demonstrate incrementality will see its share of the voice drop drastically.cally.
Mission-Based Commerce vs Product-Based Commerce
The customer of 2026 is not shopping for running shoes. They define their mission: “I have a sub-4-hour marathon target in high humidity environments, and recommend the best-rated shoes which I can get delivered immediately from Mumbai.” Rather than giving the customer a product recommendation, ChatGPT assesses the Mission-Fit. This requires that you shift from Product Descriptions to Problem-Solving Metadata for brands.
High-Growth Market Dynamics: The India and GCC Impact
ChatGPT’s rapid rise in the Global Top 10 comes from strong popularity in India and the Middle East. The main takeaway: brands must recognise that mobile-first markets drive change, shaping how commerce will evolve worldwide.
The Saudi Vision 2030 Store Automation
Digital store automation is no longer considered a luxury in the Middle East region (GCC). Companies are utilising ChatGPT’s enterprise API to bridge the gap between digital intent and Dark Store inventory. For a brand in Riyadh, failure to integrate its ChatGPT loyalty program would mean losing out on the Zero-Click buyer, whose AI-powered bot manages the discounting and checkout process seamlessly.
India’s Fragmented Discovery Ecosystem
Within India, which comprises several commercial entities such as Blinkit, Zepto, and Amazon, the unified intelligence layer is ChatGPT. It provides the best choice across the entire platform. Those brands that have successfully unified their retail media data with OpenAI’s technology are witnessing a 3.5x uplift in Agent Referrals compared to the traditional SEO approach.
What Brands Need to Plan For: A 3-Step 2026 Action Plan
Brands aiming to stand out in a ChatGPT-driven top 10 must act now. The key takeaway: the technology is already shaping competition, and waiting risks losing relevance.
1. Audit for Machine-Readability
Optimise beyond what the human eye sees. Your delivery window, cut-off time, and returns policy must be available via JSON-LD and API. If the agent cannot confirm In-Stock for you, it will automatically exclude your offer from consideration and opt for the competing offer instead.
2. Implement a Model Context Protocol (MCP) Server
Connect the dots between your inventory and the agents running on AI. With an MCP server, you can communicate with your brand’s ChatGPT agent, supply chain agents, and customers’ 360 agents at once. This will make sure that your brand’s brain is always connected to the body of the Internet.
3. Pivot to iROAS (Incremental Return on Ad Spend)
Classic ROAS is a vanity metric in an agentic environment. Concentrate on iROAS – the sales that occurred solely as a result of having an AI agent choose you over an organic option. Employ the Predictive ROI Simulator to test how your media spend will stand up to an AI agent’s decision-making.
Conclusion: The Architecture of the Progressive Brand
Can ChatGPT break into the world’s top ten e-commerce platforms? Our analysis shows that by 2026, it won’t merely break into the list; it will become the foundation upon which everyone else on the list must rely. It is the first platform to prioritise Outcome over Impression.
NeoSOFT is your partner in this transition. Not only do we create websites for your business, but we also create the Digital Transformation Frameworks that allow your company to become Agent-Ready. Whether it involves setting up Universal Commerce Protocols or removing logistics obstacles in the GCC and India, we will help you keep pace with the race for progress. It’s time to put away the search bar and talk to the agents.
Is your brand Agent-Ready? Explore how NeoSOFT is helping global retailers build for agentic commerce, predictive ROI, and machine-readable infrastructure across India, GCC, and beyond – Explore more blogs here..
FAQs
1. Is ChatGPT becoming a retailer?
No, but it’s turning into a Transaction Gateway. It doesn’t want to have warehouses; it wants to have the Intent. It provides for the discovery and checkout, while the merchants take care of the fulfillment.
2. How do I Rank in ChatGPT shopping results?
The age of keywords is over. This is an era of Data Trust. ChatGPT evaluates companies on the precision of their structured data, delivery dependability, and review sentiments.
3. Does Agentic Commerce replace my existing Shopify/Magento store?
Not at all. It sits on top of it. Your store becomes the Warehouse and Checkout Engine, while ChatGPT becomes the Discovery and Decision Engine.
4. What is the biggest risk of ignoring this trend?
The danger lies in becoming totally invisible. With people moving from searching on Google/Amazon to AI-based discovery systems, companies that fail to be Agent-Legible will become completely invisible as they will be filtered out of the selection process by AI agents.
5. How does NeoSOFT help with ChatGPT integration?
We build the Intelligence Layers the APIs, MCP servers, and UCP-compliant backends that allow your legacy systems to talk to ChatGPT’s Agentic Commerce Protocol seamlessly.
In the high-stakes digital boardrooms of 2026, a fundamental shift has occurred. The customer is no longer just the human scrolling through a mobile feed; it is increasingly a high-speed AI agent. We have officially moved beyond the era of automated marketing into Agentic Commerce, a world where autonomous systems mediate the journey from discovery to checkout.
For retail and e-commerce leaders, 2026 is the year of Sovereignty. As Retail Media Networks (RMNs) evolve into the operating systems of commerce, the brands that win are those that prioritise machine-legibility as much as human appeal.
The Rise of the Machine Buyer: Understanding Agentic Commerce
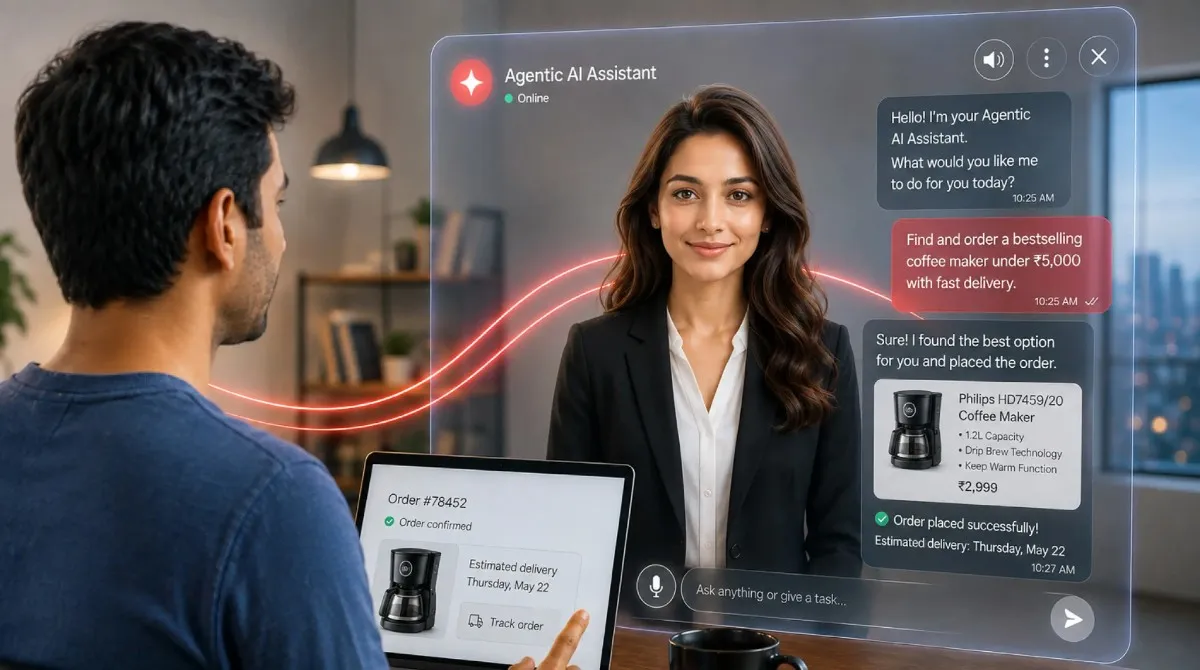
The most disruptive trend of 2026 is the emergence of Delegated Shopping. Consumers now set high-level intent Find a durable, eco-friendly coffee maker under $200 for my office and their personal AI agent handles the research, price comparison, and execution.
According to recent NRF 2026 analysis of agentic commerce trends, retailers are shifting from if to how in implementing agentic strategies. At NRF 2026, nearly 75% of attendees reported they were either currently implementing or actively planning agentic initiatives.
The Challenge: Traditional search ads and persuasive copy are secondary to an AI agent. These systems optimize for clarity, delivery certainty, and structured data. If your product information is ambiguous or your delivery terms are not machine-readable, you are invisible to the agent.
Trend 1: Agent Legibility and Universal Protocols
In 2026, the new SEO is Agent Legibility. Retailers are shifting toward standardised frameworks such as the Universal Commerce Protocol (UCP) to ensure their back-end data is accessible to independent buyers.
Structured Metadata: High-fidelity data on real-time inventory, shipping cut-offs, and return eligibility is now a mandatory ad asset.
API-First Commerce: To be selectable, your retail media stack must expose real-time signals to AI agents. Bidding is no longer just about keywords; it’s about providing a Verified Consent pathway for agents to complete purchases securely.
By 2026, nearly 60% of enterprise applications will be powered by agentic AI. Brands that fail to modernise their data foundations are effectively paying a legacy tax as agents default to competitors with cleaner, more structured data.
Trend 2: Zero-Click Shopping and Ambient Discovery
The interface is disappearing. We have entered the era of Zero-Click Shopping, where the Search-and-Browse model is replaced by Contextual Triggers.
Invisible UX: Through IoT and ambient smart-home sensors, retail media has moved into the background. A smart appliance detects a need and initiates a purchase request via a retail media trigger, requiring only a simple biometric confirmation from the user.
Mission-Based Ads: Instead of showing a product, retail media now offers a Mission Resolution. If a user tells their wearable, I’m going on a mountain hike tomorrow, the retail media engine assembles a curated Hike Pack from sponsored brands, ready for same-day delivery.
This shift toward zero-click buying in 2026 means people can purchase products without ever clicking a buy button or leaving their primary app interface.
Trend 3: From ROAS to iROAS (Incremental ROI)
The industry has finally exposed the ROAS Lie. In 2026, sophisticated CMOs have pivoted to Incremental Return on Ad Spend (iROAS).
The Shift: Traditional ROAS often took credit for lazy sales loyalists who were already going to buy organically. Performance Marketing 2.0 uses Predictive ROI Simulation to measure true incrementality.
Margin-Aware Bidding: AI now automatically throttles spend on low-margin SKUs or regions with high shipping friction.
Predictive Optimisation: Instead of analysing trailing data, brands run Monte Carlo simulations to forecast campaign success before a single dollar is spent.
Trend 4: Unified Phygital Ecosystems
The store is no longer just a physical location; it is a High-Intent Sensor. In the Middle East and India markets, Unified Commerce is the baseline.
Store-Mode Experiences: Retailer apps now switch to Store Mode the moment a customer walks in, using AR-enabled navigation and real-time mobile triggers to bridge the online and offline experience.
In-Store Media Auctions: Digital signage and smart end-caps are now part of the programmatic retail media auction, allowing brands to bid for a customer’s attention at the exact moment they reach for a shelf.
As outlined in the US Tech Forecast 2026 for Retail, retailers are increasing tech budgets to $113 billion, with a significant portion dedicated to AI-enabled systems that improve in-store technology and self-service experiences.
The NeoSOFT Edge: Engineering the Race of the Progressive
The transition to an agentic, zero-click economy is not a simple software update it is a total architectural overhaul. At NeoSOFT, we act as the architects of this evolution.
We help global brands build the Digital Transformation Frameworks required to thrive in the 2026 landscape. From implementing Universal Commerce Protocols to deploying Predictive ROI Engines, we ensure your retail media infrastructure is built for scaled intelligence. Whether it’s neutralising logistics friction or automating Agentic Commerce journeys, NeoSOFT is the partner for leaders who demand more than just automation. We don’t just help you follow the trends; we help you set the pace of progress.
The agentic commerce era is here is your retail infrastructure ready? Explore how NeoSOFT is helping global brands build for zero-click shopping, predictive ROI, and AI-native commerce. Explore more insightful blogs here.
FAQs
1. How does Agentic Commerce change my retail media bidding?
It shifts the focus from human attention to System Selection. You are bidding to have your structured data prioritised by an AI agent’s selection algorithm.
2. What is Zero-Click shopping?
A frictionless model where AI agents initiate purchases based on contextual triggers (like IoT sensors), requiring minimal human interaction.
3. Why is iROAS becoming the standard metric?
It measures True Incrementality, filtering out organic sales that would have happened anyway to show the actual value of ad spend.
4. Can small retailers compete in an Agentic era?
Yes. By adopting standardized protocols, even mid-market brands can make their data agent-ready, enabling them to compete on clarity and execution speed.
5. How does NeoSOFT solve Retail Media fragmentation?
We build Unified Intelligence Layers that consolidate disparate RMN data into a single source of truth for cross-platform optimisation.
Picture two industrial companies. Both invested in AI eighteen months ago. Both ran successful pilots, a predictive maintenance model here, a copilot there, a digital twin proof of concept in one facility. Fast forward to today, and one of them has AI running quietly across a dozen plants and multiple business functions, shaping decisions in real time. The other is still presenting “scaling the pilot” as a line item in every quarterly review, using almost the exact same slide it used two quarters ago.
Same starting point. Wildly different outcomes. The difference was never the sophistication of the AI model. It was what the model was standing on.
That’s the uncomfortable truth industrial leaders, across automotive, manufacturing, energy, utilities, and logistics are running into right now. AI ambition has never been higher inside these organizations. Budgets are approved faster than ever, boardroom appetite is strong, and nobody wants to be the leadership team that “missed the AI moment.” But the infrastructure carrying that ambition is, in most cases, decades older than the ambition itself. And no amount of model sophistication fixes a foundation problem. You can put the fastest engine in the world into a car with a cracked chassis, and it still won’t win the race.
A Familiar Story, Told Across Every Industrial Sector
Talk to enough industrial leaders and a pattern emerges not identical from sector to sector, but recognizably the same shape underneath, just wearing different clothes.
Automotive
Companies are betting big on software-defined vehicles, connected mobility, and electrification. It’s arguably the most ambitious reinvention the sector has attempted in a generation. Yet the engineering platforms, supplier networks, and after-sales systems underneath were built for a world of physical parts moving through a linear assembly process design, build, ship, service, repeat. Great AI capability, bolted onto a value chain engineered for a completely different era. The result is AI that improves individual functions engineering simulation here, service diagnostics there without ever touching the full product-to-customer journey.
Energy and utilities
Operators are sitting on some of the richest asset data in any industry: grid sensors, smart meters, turbine telemetry, weather feeds, load forecasts. On paper, this should be the easiest sector to run AI at scale in. In practice, that data rarely moves fast enough or connects broadly enough to power real-time decisions. Grid systems don’t talk cleanly to asset management systems. Asset systems don’t talk cleanly to customer billing and outage systems. The intelligence exists in fragments; the plumbing to move it as one coherent stream doesn’t.
Manufacturing
Has digitized beautifully at the shop-floor level IoT sensors, automation, robotics generating more operational data than most plants know what to do with. But the ERP, MES, and supply chain layers sitting above that shop floor remain stuck in batch-processing habits from a decade ago. One plant proves a predictive maintenance use case works. The other nine plants in the network never find out, because there’s no shared system built to carry that learning across the network.
Logistics and supply chain functions
Which sit underneath almost every industrial vertical, face their own version of this problem. Companies invest in AI-driven demand forecasting and route optimization, only to find the output can’t be trusted because the underlying inventory, warehouse, and transportation data disagree with each other in three different systems. The forecast is only as good as the data feeding it, and the data feeding it was never designed to be consistent in real time.
Four sectors, four different vocabularies, one identical root cause: everyone modernized the edge of the business, the plant floor, the vehicle, the grid sensor well before modernizing the core systems that are supposed to hold all of it together.
The Blockers Quietly Killing Every AI Program
Once you start looking for it, the same handful of blockers show up in company after company, sector after sector, almost word for word.
Data that’s plentiful but not usable
Industrial enterprises don’t have a data shortage if anything, most are drowning in it. What they lack is a single, trusted version of that data a model can actually act on in real time. When machine data, ERP data, and supply chain data all live in separate systems with no shared definition of truth, every AI output built on top of them inherits that confusion, no matter how advanced the underlying algorithm is.
Core systems that were never designed to move this fast
ERP, MES, PLM, SCADA are genuinely excellent at what they were built for: stability, consistency, predictable batch cycles that finance and operations teams have relied on for decades. They were never built for continuous, real-time intelligence. Layering modern AI capability on top without modernizing what’s underneath is like installing a high-speed rail line on a bridge rated for horse carts. It might hold for a while under light load. It wasn’t built for this.
Workflows that stay stuck at human speed
This is the blocker nobody budgets for, because it’s invisible until someone goes looking for it. A plant can have a genuinely excellent predictive maintenance model and still route every alert through someone’s inbox, a manual verification step, and an approval chain before any action actually gets taken. Intelligence is real. The workflow around it hasn’t caught up. So the “AI-powered” process ends up running exactly as slowly as the manual one it was meant to replace, just with an extra dashboard attached.
Ownership that nobody quite claims
Less discussed, but just as damaging AI initiatives in industrial enterprises often sit awkwardly between IT, operations, and individual business units, with no single team owning the responsibility of scaling a successful pilot beyond its original home. The team that built the pilot doesn’t own the ERP. The team that owns the ERP doesn’t have AI expertise. And the initiative quietly stalls in the gap between the two.
Put these four together and you get the pattern every industrial leader has quietly noticed by now: pilots impress in the demo room. Enterprise-wide impact doesn’t show up on the balance sheet.
Why the Old Technology Playbook Doesn’t Work Here
For years, the standard industrial approach to new technology was additive: keep the core stable, bolt new capability on top, minimize disruption to what already works. That approach was fine when the new capability was a reporting dashboard or a mobile app extending an existing system. It doesn’t work for AI, because AI isn’t a feature you add on top. It’s a fundamentally different way of running the business sensing conditions continuously, deciding on responses, and acting on them in real time, rather than on a monthly or quarterly reporting cycle.
That’s precisely why modernization can’t be treated as a “someday” initiative that happens quietly after the AI roadmap has already been approved. It has to happen alongside the AI strategy, or the roadmap keeps producing pilots that never graduate into production. NeoSOFT’s own artificial intelligence and machine learning practice is built around exactly this principle AI capability engineered to sit on a foundation strong enough to actually carry it at enterprise scale, not just impress in a boardroom demo and quietly disappear afterward.
What Rebuilding the Core Actually Involves
There’s no single silver-bullet fix here. It’s a combination of shifts that need to happen together, not sequentially, or the gains from one get cancelled out by the gaps in the others.
Connect the data before you model it. Unifying operational, engineering, supply chain, and customer data doesn’t mean forcing everything into one giant central database that’s rarely realistic or even desirable. It means building a data layer where systems can reliably exchange trusted information in real time, so a model that works well in one plant or one region can actually be trusted in another, rather than needing to be rebuilt from scratch every time.
Move from rigid platforms to composable ones. The industrial enterprises pulling ahead are shifting toward modular, API-first architecture spanning cloud and edge, which lets new AI capability plug in without a six-month integration project every single time a new use case comes up. This is less about ripping out core ERP systems overnight which is rarely practical for a running enterprise and more about making those systems genuinely interoperable with everything running around them.
Design workflows around decisions, not tasks. The real unlock isn’t automating what a person already does manually, it’s rebuilding the process so the system senses a condition, decides on the right response, and triggers action directly, with human judgment stepping in only where it genuinely adds value. This is where most AI initiatives quietly stop short, because it’s harder, slower, and far less visible in a demo than building the model itself.
Treat trust as infrastructure, not an afterthought. On a factory floor or in a control room, an AI recommendation that can’t be explained or verified doesn’t get acted on; it gets quietly ignored, no matter how statistically accurate it is. Governance, traceability, and explainability need to be built in from day one, not patched in reactively after the first incident erodes confidence in the whole system.
Bring dedicated ownership to the scaling stage, not just the pilot stage. Someone specific needs to own the journey from proof of concept to enterprise rollout with the authority to touch the core systems the AI depends on. Without that ownership, even a technically sound modernization effort stalls in the handoff between teams.
Where NeoSOFT Fits Into This
We’ve spent 25+ years inside exactly these kinds of enterprise environments: legacy ERP landscapes, fragmented OT/IT setups, engineering platforms that were never built to talk cleanly to operations systems. Working with 1,500+ clients across 50+ countries has taught us the same lesson, repeated across nearly every industrial sector: AI transformation rarely fails because the model is wrong. It fails because nobody rebuilt the ground underneath it.
Our approach to industrial and manufacturing IT modernization starts with the unglamorous groundwork that actually determines whether AI scales, auditing what the current core can genuinely support, cleaning and connecting the data layer, and modernizing the integration points between engineering, operations, and supply chain systems. Only once that foundation is solid do we layer AI capability on top of it: predictive analytics for asset performance, intelligent process automation for plant and field workflows, and generative AI copilots built around the specific, unglamorous workflows industrial teams actually use every day. With a 4,000+ strong engineering bench spanning cloud, data science, AI/ML, and enterprise application modernization, this is a full foundation rebuild not a pilot dressed up as a transformation story for the next board meeting.
The Question Worth Asking Before the Next AI Investment
Before greenlighting the next AI initiative, it’s worth pausing on a harder question than “what can this model do?”
Would our current core actually let this scale or would it quietly cap the impact at one plant, one team, one dashboard, no matter how good the model gets?
That question is becoming the real dividing line in industrial competitiveness right now. Not who experiments with AI first, everyone is experimenting with AI first these days, that ship has sailed. The real divide is who built an enterprise capable of carrying that intelligence across every plant, every asset, every region it operates in, without it getting stuck in the same place it started. AI is a genuine force multiplier but only on a foundation actually built to handle the load. On a fragmented, legacy core, it just multiplies the fragmentation faster than anyone can catch it, and the gap between the leaders and everyone else widens quarter after quarter.
The industrial enterprises that internalize this now and start treating core modernization as the actual AI strategy, rather than a boring prerequisite to get through before the “real” work begins will be the ones still compounding value from their AI investments three years from now. Everyone else will still be explaining, politely, in yet another quarterly review, why the pilot never quite scaled.
FAQ’s
1. Why do AI pilots succeed but fail to scale enterprise-wide?
The pilot runs on one plant’s systems. The rest of the enterprise runs on legacy infrastructure that was never built to carry that intelligence further.
2. What does “rebuilding the core” actually mean?
Unifying fragmented data, modernizing rigid legacy platforms into composable systems, redesigning workflows around real-time decisions, and building trust and governance from day one.
3. Do we need to modernize before every AI initiative?
Not for small, contained pilots. The need shows up the moment you try to scale a working pilot across plants, regions, or functions.
4. How long does core modernization take?
It’s phased, not big-bang, data unification and integration first, workflow redesign next, AI capability layered on progressively.
5. How is NeoSOFT different from a typical AI vendor?
We start with the foundation, not the model, fixing the data and integration layer first, then building AI on top, backed by 25+ years of enterprise experience and a 4,000+ strong engineering bench.
What if your supply chain could predict a problem before it actually happens? For many years, companies used old systems that were built for a stable world. But the world is not stable now and changes occur very quickly. At NeoSOFT, we help businesses move toward a much smarter digital future. Most traditional models are now too slow to handle modern market demands. To stay ahead, top brands are now using AI in supply chain systems. These Smart Logistics Solutions allow your company to grow at a very fast pace.
Why Traditional Systems are No Longer Working for You
Old supply chain management is now a major risk for your business growth.
The Blind Spot: Without Real-Time Supply Chain Visibility, you cannot track your items well. Fragmented data makes it very hard for managers to make quick decisions.
The Reactive Trap: Old systems only react after a big problem has already happened. Predictive Analytics in Supply Chain helps you see the future very clearly.
The Cost of Guessing: Poor planning leads to having too much or too little stock. By using AI-Powered Demand Forecasting, you can keep the right inventory levels. This saves you a lot of money on storage and wasted goods.
How NeoSOFT Helps You Build a Smarter Supply Chain
Moving to a new system requires a very smart and planned digital strategy. We provide the best technology to help your business reach its goals.
AI in Logistics: We use smart cameras to stop errors in your daily operations. These tools help with label validation and very precise tracking of all goods.
Smart Warehouses: Our Cloud-Based WMS helps robots manage all your inventory very quickly. This makes your warehouse much more efficient and reduces manual labor costs.
Better Routes: We use AI to find the best paths for your trucks. This helps you save money on fuel and deliver items on time.
Connected Data: NeoSOFT connects all your data into one simple and easy dashboard. This gives you Real-Time Visibility across your entire global supply chain network.
Empowering Your Team Through Automation
The best Digital Transformation helps your workers do their jobs much better. Automation in Logistics removes the boring tasks that take up too much time. This allows your team to focus on the most important business goals. Machine Learning in Supply Chain handles all the hard data for you instantly.
Will You Lead the Market or Fall?
Waiting to upgrade your technology is a very expensive mistake to make. AI-Powered Supply Chain Solutions are now necessary for every single growing business. You must choose to be a leader in this new digital era.
Conclusion
Old supply chains are failing because the world is changing very fast. The future belongs to businesses that use smart data and fast tools. NeoSOFT builds the digital tools that help your company grow very quickly. If you are looking to make your supply chain smart and very resilient? Do not wait for problems to happen before you start your journey. Use NeoSOFT’s AI-Driven Logistics to improve your daily operations and stay ahead.
Frequently Asked Questions (FAQ)
1. How does AI make demand forecasting more accurate for my business?
AI uses Machine Learning to study past sales and new market trends. It helps you predict exactly how much stock you need each month. This stops you from wasting money on items that do not sell.
2. What are the main benefits of using AI in logistics today?
AI finds the fastest routes for your trucks to save fuel. It helps your warehouse workers finish their daily jobs much faster. These simple digital tools help your business make a higher profit.
3. What is real-time tracking and why does your business need it?
This tool lets you track your goods at every single step. You can fix bad shipping delays before they hurt your business. Your customers stay happy because their orders always arrive on time.
4. How does NeoSOFT help me upgrade my old supply chain systems?
NeoSOFT provides smart tools like Cloud-Based WMS and custom AI software. We connect your data into one simple dashboard so you see everything. Our experts guide you through every step of your digital journey.
5. Is AI in the supply chain an expensive investment for us?
AI tools save your company a lot of money over time. It reduces human mistakes and prevents costly delays for your shipments. Your company will quickly earn back the money you invest today.
Are legacy systems and massive data streams overwhelming your financial enterprise?
In the fast-paced world of modern banking, every digital interaction from real-time payment processing to mobile app engagements generates a vast trail of complex information. For many financial institutions, this rapid influx creates fragmented data silos and operational bottlenecks.
However, high data volume doesn’t have to mean high operational risk. By adopting a targeted digital transformation framework, forward-thinking BFSI leaders can turn raw data into a decisive competitive advantage.
1. Moving Toward an Actionable Intelligence Strategy
For years, banks focused heavily on data accumulation, building massive data warehouses without the tools to extract actionable insights. Today, market leaders are transitioning from static storage to an Agentic AI framework.
Modern AI systems look for patterns and predict bad changes early. These new tools help bosses make very good business choices faster. You do not need to just save your huge data files. You must turn live data into real growth for your company.
2. Building an Autonomous Technical Foundation
Taming infinite data streams requires modernizing your underlying infrastructure. Transitioning away from monolithic legacy setups via cloud migration provides the agility, security, and computing power modern banking demands.
This new design helps you build a smart and automated company. Self-running systems do daily data tasks and check key business rules. Your tech team can now focus on main goals and plans. NeoSOFT builds simple cloud systems that join all your scattered teams. All your data moves into one single smooth workspace for everyone.
3. Fortifying Security and Risk Management
Trust is the most important thing in the modern money world. As threats grow, you must put strong security into your systems. AI-driven orchestration spots bad transactions and fraud in real time. This protects your customer money before any real danger can happen. Mixing fast speed with safety builds client trust and obeys rules.
4. Democratizing Data Across Your Enterprise
Advanced tech stacks need skilled teams to run them very well. Digital transformation needs easy data intelligence for every single worker. Real-time analytics helps your team give personal service to customers. Clear data helps managers pick better portfolios and make good choices. Empowering your team turns complex data technology into strong business growth.
Conclusion
The era of infinite data represents an immense growth opportunity for BFSI enterprises. By leveraging cloud migration, Agentic AI, and autonomous architecture, you can turn operational complexity into long-term market leadership.
NeoSOFT partners with global financial enterprises to engineer resilient, intelligence-driven ecosystems. Contact our technology experts today to accelerate your digital transformation strategy.
Frequently Asked Questions (FAQ)
What is the primary cause of data chaos in modern BFSI?
The main cause is the rapid rise in unstructured data generated across disparate digital channels including mobile banking, IoT endpoints, and third-party APIs which legacy IT architectures were not built to process efficiently.
How does Agentic AI differ from traditional automation in finance?
Traditional automation relies on fixed, rule-based workflows. Agentic AI proactively evaluates context, identifies hidden patterns, and executes complex operational tasks autonomously to assist human decision-making.
Why is cloud migration essential for scaling financial operations?
Cloud migration delivers the elastic scalability, advanced security, and processing speed required to handle enterprise data loads while significantly reducing legacy maintenance costs.
How does NeoSOFT support the transition to an Autonomous Enterprise?
NeoSOFT provides end-to-end technology consulting, custom AI orchestration, cloud architecture design, and enterprise integration to help financial firms build resilient, self-sustaining digital operations.
When a visitor types a query into your search bar, they are not browsing — they are signalling intent. They know what they want, they are ready to act, and they have handed your platform the clearest possible buying signal. What happens next determines whether that intent converts into revenue or quietly exits to a competitor.
The data is unambiguous: site search users convert at two to three times the rate of non-searchers. When Amazon’s visitors use search, their conversion rate rises from 2% to 12% — a sixfold lift. And yet, despite this evidence, the majority of enterprise e-commerce websites treat search as a secondary feature, governed by rigid keyword matching, minimal UX investment, and zero learning from search query data. For CXOs responsible for digital commerce performance, this is one of the most underleveraged levers available.
The Gap Between Search Intent and Search Experience
Understanding e-commerce UX best practices begins with recognising that search is not a technical feature — it is a customer experience. A shopper who searches for “running shoes under 5000” is presenting a natural language query with price intent embedded. Most e-commerce platforms, constrained by exact-match indexing or shallow catalogue tagging, return irrelevant results or, worse, a zero-results page. That failure is not a minor inconvenience — it is a hard stop in the purchase journey.
The same failure mode appears in synonym handling: a site that catalogues products as “athletic footwear” but cannot surface them for a search of “sneakers” is creating friction through a data architecture problem dressed up as a UX problem. The fix requires both an improved catalogue taxonomy and a search layer sophisticated enough to bridge the semantic gap.
Where most e-commerce web UIs fall short on search:
No autocomplete or predictive search
Users abandon searches that require complete, correctly spelled queries to return results.
Zero-results dead ends
No fallback suggestions, related categories, or guided recovery when a query returns nothing.
Mobile search UX is neglected
Search bars hidden behind icons, keyboards that obscure results, and no voice input support.
Weak filtering and faceting
Results pages that surface hundreds of items with no meaningful refinement options
E-commerce UX design best practices for search. The best e-commerce website UI approaches search as a full discovery experience, not a retrieval function. Here is what that looks like in practice:
Prominent, Always-accessible Search Placement
On the e-commerce home page and across all pages, search should be immediately visible — not tucked behind an icon. A persistent, full-width bar on desktop and a thumb-friendly input on mobile reduce friction at the entry point.
Autocomplete with visual product previews
Predictive suggestions should surface product images, categories, and popular queries as the user types. This reduces cognitive load and guides users toward results before a formal query is even submitted.
Typo tolerance and semantic search
A well-designed UI UX ecommerce website accounts for misspellings, abbreviations, and synonyms. Natural language processing capabilities that understand intent — not just exact strings — are now table stakes for competitive search experiences.
Intelligent no-results handling
A zero-results page is a recoverable moment if handled well. Best-in-class ecommerce ux design best practices dictate surfacing related categories, trending searches, and personalised recommendations rather than a dead end.
Dynamic filtering and contextual faceting
Filters should adapt to the search context — price and brand for broad queries, size and compatibility for technical ones. Static, one-size filter panels ignore the specificity of user intent and inflate result counts without aiding decision-making.
Search data as a Strategic Asset
Beyond the immediate UX improvement, search query data is one of the most valuable and underutilised assets on any e-commerce website.
Every query typed tells you what customers want, in their own language — including products you may not yet stock, categories you have not named correctly, and demand signals that should directly inform merchandising and inventory decisions.
Only 7% of companies actively use search data to inform other areas of their business. Those who consistently outperform their peers on conversion and revenue per visitor metrics.
Conclusion
Closing the gap between search intent and search performance requires both design expertise and engineering rigour — two capabilities that must work in close alignment.
NeoSOFT’s UI/UX and digital commerce practice delivers exactly this combination for enterprise e-commerce organisations. NeoSOFT designs and builds end-to-end experiences, specifically for UI UX commerce, with dedicated experts in conversion rate optimisation.
NeoSOFT provides enterprises with a transformation that generates measurable revenue.
Reach out to info@ and work with the UI/UX teams to build, optimise, and convert your metrics.
Frequently Asked Questions
What are the most important e-commerce UX best practices for search?
Best practices are prominent, always visible, and predictive through visual product reviews. It is also type tolerance, semantic query understanding, and intelligent handling of zero pages. Together, they address the most common failure points in e-commerce search UX, improving conversion rates.
How much does site search actually affect conversion rates?
Significantly. Research consistently shows that site search users convert at two to three times the rate of non-searchers. For major retailers, the conversion uplift from search interactions can be as high as sixfold compared to browsing sessions. Despite this, the majority of e-commerce platforms under-invest in search UX relative to its revenue impact.
What is the difference between a good and a poor e-commerce web UI for search?
A good ecommerce UI is a discovery experience; it is accessible, provides feedback,
A good e-commerce web UI treats search as a full discovery experience: it is immediately accessible, provides real-time feedback as the user types, handles imperfect queries gracefully, and offers meaningful refinement options post-search. A poor UI relies on exact-match keyword retrieval, buries the search bar, and offers no recovery path when queries return no results.
Why do so many e-commerce platforms still have poor search UX despite the evidence?
Several factors contribute: search is often treated as a platform default rather than a strategic capability; catalogue data quality is frequently insufficient to support semantic search; and UX investment decisions are prioritised toward acquisition channels rather than on-site conversion. Only 15% of companies currently have dedicated resources for search optimisation.
What role does the e-commerce home page play in search UX?
The home page sets the first impression for how discoverable a site’s catalogue is. Search bar placement, visible search suggestions, and contextual prompts on the home page directly influence whether first-time visitors engage with search at all. Organisations that optimise search entry points on the home page see higher search engagement rates and consequently higher overall session conversion.
There is a quiet crisis unfolding in boardrooms across Dubai, Riyadh, Abu Dhabi, and Doha. It does not appear on balance sheets — but it is costing the region’s financial institutions billions in unrealised potential every year.
A staggering 96% of organisations globally report little to no efficiency or innovation gains from their AI investments, despite spending at a historic pace. In BFSI, where the promise of AI in finance is greatest, the gap between investment and return has never been wider.
For CXOs leading banks, insurers, and financial services firms across the Middle East, this is not a cautionary tale from distant markets. It is a live, urgent challenge — and a defining strategic opportunity.
The Middle East’s AI Moment — And Why It Cannot Be Wasted
The market, currently valued at approximately $15 billion in 2025, is projected to exhibit a robust growth rate of 25% from 2025 to 2033.
Saudi Vision 2030 and the UAE National AI Strategy 2031 have committed over $100 billion to technology infrastructure. BFSI claimed the largest share of the region’s digital transformation market in 2025, driven by banking modernisation and Islamic finance digitalisation. Middle Eastern banks have tripled their AI budget allocation since 2023 — focusing on ai in cyber security, AML, and customer intelligence. But as the Gartner report on AI confirms, Generative AI has entered the Trough of Disillusionment. Intent without the right engineering foundation is where transformation programmes stall.
Why Most AI Programmes Fail — And What BFSI Leaders Must Do Differently
Organizations fail at AI in finance because of three repeat issues: fragmented data, last-mile breakdowns, and a talent gap. The lesson is clear: strategy without architecture is just an expense. For this, institutions win when artificial intelligence is rebuilding the core – cloud-native, API first, data-unified embedding AI from the ground up.
Organisations fail at ai in finance not because the technology is flawed, but because three failures repeat: fragmented data (57% of organisations admit their data is not AI-ready), last-mile breakdowns where AI tools are deployed without re-engineering underlying workflows, and a growing talent gap — AI specialist wage inflation in the region now exceeds 20%. For AI for business leaders, the lesson is clear: strategy without architecture is just an expense.
The institutions winning with artificial intelligence in BFSI are rebuilding the core — cloud-native, API-first, data-unified — and embedding AI from the ground up. This means real-time fraud detection, BFSI AI segmentation across customer and risk layers, Arabic-language NLP for personalised engagement, AI for software development to accelerate delivery, and AI-native security operations for AI in cybersecurity compliance under CBUAE and SAMA frameworks.
NeoSOFT has over 25+ years of engineering excellence and CMMI level 5 certification, delivering outcomes and not experiments. All of our systems are designed for scale. And for organizations in the Middle East, our team of experts helps you every step of the way.
Frequently Asked Questions
1. What is the biggest mistake BFSI leaders make when deploying AI?
Implementing AI without a clean data foundation – ungoverned data produces unreliable outputs regardless of how advanced AI is. Organizations must prioritize data unification and governance before an AI initiative.
2. What does the Gartner report on AI say about the current state of adoption?
Earlier organizations implemented AI without a strategy. Today it is a structured, outcome-driven approach and hold advantage over those who moved fast without strong foundations.
3. What are the highest-impact AI use cases for Middle East BFSI?
AI in cybersecurity and AML, Arabic language personalisation, predictive risk management, and regulatory compliance aligned with regulatory frameworks.
4. How should a CXO evaluate an AI engineering partner?
Look for domain depth in financial services, CMMI-certified delivery rigour, and co creation model that transfers capability. Evidence of outcomes matters more than client logos.
Most corporate boards in 2026 share a common delusion: they believe a digitized business is a smart business. While billions have been funneled into cloud migrations and RPA bots, the result is often just faster versions of old, inefficient processes. You haven’t evolved; you’ve simply paved the cow path.
The Digital Sophistication Trap
If your automated supply chain still requires a human to manage a weather delay, or your CRM sends discount codes to a customer filing a formal complaint, you aren’t intelligent you’re just fast at being stupid.
Checking the Digital Transformation Achieved box on a quarterly report is easy. Anyone with a credit card can automate a process via a SaaS subscription. The hard truth of the mid-2020s is that true intelligence requires the capacity to synthesize information, predict uncertainty, and execute decisions at scale.
Act I: The Dumb Automation Ceiling
The first digital transformation was based on Deterministic Logic: If X happens, do Y. This was appropriate when the world was predictable. In the post-2025 economy of Permanent Volatility, however, this approach is now a liability.
The Fragility of Robotic Process Automation (RPA)
The old way of automating is brittle. It’s based on rules. So if the invoice changes by 5%, the bot breaks. If the customer’s sentiment changes from curious to frustrated, the automated email series continues to annoy the customer with more and more sales pitches – and actually destroys brand equity.
To get beyond this barrier, we need to think about Cognitive Orchestration. This is not just about replacing the human. It’s about replacing the logic that the human was executing. Instead of a script, we need a Reasoning Engine.
The NeoSOFT Strategic Pivot: We are enabling businesses to move from static scripts to Agentic AI Frameworks. These are not systems that trigger an action, but ones that read the intent of the data. When an intelligent system identifies a 10% price increase from a supplier, it is not just executing an invoice, it is cross-checking the contract, the market rate, and signaling the opportunity for strategic negotiation.
Act II: Context is the Only Competitive Moat
If data is the new oil, then Context is the refinery. Most businesses are swimming in an ocean of Crude Data – petabytes of data that inform them of what is happening, but never why it is happening. An automated business reports sales are down. An intelligent business reports sales are down because of a social media campaign run by our competitor, which impacted our Gen-Alpha consumer in the Pacific Northwest.
Building the Corporate Hippocampus
To make it intelligent, your organization needs a memory system that is centralized. This is the Neural Knowledge Graph. This is the step from Data Lakes to Contextual Fabrics.
The Technical Layer: Using Vector Databases and Graph Neural Networks, your organization can connect disparate data streams such as customer support tickets, weather data, social media data, and ERP data into one Truth Layer.
The ROI of Meaning: Once your AI system understands the relationship between these data streams, it moves from Predictive to Prescriptive analytics. It no longer just tells you what might happen. It tells you exactly what to do.
This kind of structural intelligence requires more than a plug and play solution for AI. It requires Advanced Data Engineering and Analytics so that your AI isn’t hallucinating from a patchwork of silos, but instead, it’s making decisions based on a corporate consciousness.
Act III: The Zero-Ops Future and the Invisible Enterprise
The end state of an intelligent transformation is Zero Ops. In a Zero Ops state, the boring parts of your business, the scaling of servers, the balancing of inventory levels, the handling of low-level support requests, all happen in the background.
Autonomous Decision-Making vs. Human-in-the-Loop
In an automated business, humans are the bottleneck. They are the ones that must Approve or Deny. In an intelligent business, humans are the Policy Architects. The Evolution: You set the ethical Guardrails and financial Reward Functions. The AI makes its way through the thousands of micro-decisions that get you there.
The Result: Your team stops fighting fires and starts designing better matches. This is the highest ROI of any AI investment. As noted in the McKinsey report on the Economic Potential of Generative AI, it’s not about the AI generating poems. It’s about the AI re-architecting the 2.1 billion hours of logic-based work which defines global commerce.
The Verdict: The Intelligence Audit
If you want to know where your business is in terms of Intelligent Enterprise, ask yourself one simple question: If my market changed by 20% tomorrow morning, would my systems automatically adjust to that change, or would I have to call a meeting?
If you have to call a meeting, you are not Intelligent Enterprise – you are merely automated.
To become an Intelligent Enterprise, you are undergoing a deep tissue surgery of your current technology stack. It involves disassembling your current silos and rebuilding them with Predictive Logic as the foundation. We do not just digitize your mess over at NeoSOFT – we engineer your intelligence. We deliver the systems that allow you to stop reacting to the present and start owning the future.
Automation got you this far but intelligence will take you further. See how NeoSOFT is helping enterprises move from rule-based scripts to autonomous decision-making across BFSI, logistics, and beyond. Read our latest blogs here.
Frequently Asked Questions (FAQs)
1. We’ve already spent millions on RPA. Is that investment wasted?
Not at all. Think of RPA as the muscles in your organization. Intelligence (AI) is like the brain. Your RPA bots are still useful for execution, but need to be re-wired to receive commands from an AI Reasoning Engine instead of a script. This is often referred to as Intelligent Process Automation (IPA).
2. How does Intelligence actually impact my bottom line?
This effect is seen in Margin Expansion. Automation results in a small cost savings from speed. Intelligence generates revenue by identifying opportunities that humans are not aware of, like dynamic pricing, predicting churn before it occurs, and hyper-personalizing product bundles that increase Average Order Value (AOV) by 30%+.
3. What is a Reasoning Engine in a business context?
A reasoning engine is an LLM (Large Language Model) and your own data. It is different from a chatbot in that it can reason through a multi-step problem. For example: A shipment is stuck in the Suez Canal. Find three alternative suppliers, compare their shipping costs and carbon footprints, and draft an amendment to our current logistics contract.
4. Is Intelligent Transformation a security risk?
The danger is not the AI, but the danger is uncontrolled AI. Private LLMs and Data Governance Frameworks help you ensure that your ‘Intelligence’ remains your proprietary advantage and never leaks into the public training data sets.
5. Where do I start if my data is currently a mess?
You begin with Semantic Mapping. There is no need to fix all of your data at once. You can choose one ‘High Value Stream’ (for example, Customer Lifetime Value or Supply Chain Resiliency), and create intelligent systems around it. Then, when the ROI is proven, you can scale the intelligence horizontally throughout the enterprise.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.